
Furthermore, trust account rules may mandate regular audits or inspections of trust accounts by legal regulatory authorities to verify compliance with the established guidelines. Understanding and adhering to these key components of trust account rules is essential for lawyers to fulfill their ethical and legal obligations in managing client funds. Can I manage my firm’s trust accounts manually, or do I need specialized software? While it is possible to manage trust accounts manually, doing so increases the risk of errors and compliance issues due to the complexity and meticulousness required in trust accounting.
Setting Up Trust Accounts
An escrow account is generally used to hold funds or assets during transactions, like real estate deals, and is managed by a neutral third party. In contrast, a client trust account is specifically for holding and managing client funds related to legal services. Lawyers have a fiduciary duty toward their clients, but common trust accounting errors can at times prevent lawyers from upholding those duties to the fullest extent possible. It’s a lot to keep track of, but it’s important—both for your clients’ peace of mind when they hand over large sums to your firm for work that hasn’t been done yet and for keeping you compliant. If selected for a random audit, your firm needs to be able to produce accurate trust accounting records and reconciliation reports.
Trust Ledger

The length of time a lawyer can hold money in trust varies depending on the specific circumstances and the laws and regulations of the jurisdiction in which the lawyer practices. In general, a lawyer should only hold funds in trust for as long as is reasonably necessary to fulfill the purpose for which the funds were entrusted to them. Even though the law firm holds the figurative keys to a trust account, the money in the account belongs to the client.1 This is why there are such strict regulations for how the money in the account must be handled and how the books must be kept. Trust accounts allow lawyers to charge retainer fees, giving them peace of mind that clients can pay their bills—and as such, most lawyers will use trust accounts at some point in their careers.
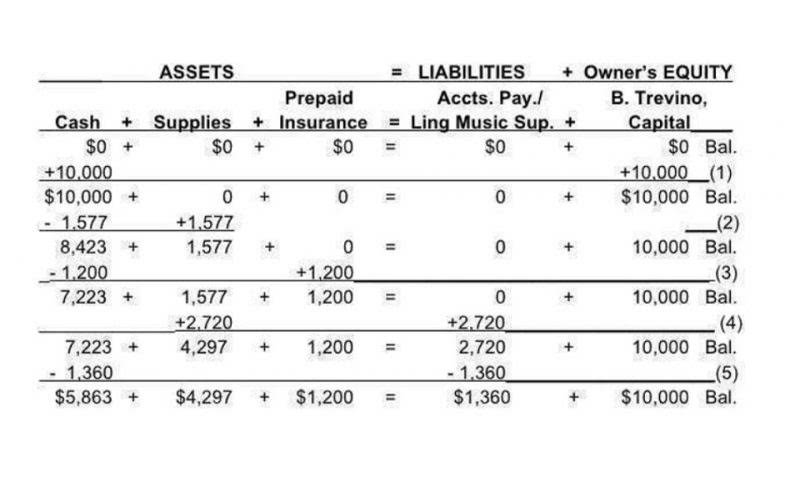

Improper record-keeping and tracking of client funds
- Navigating Taxes for Legal ProfessionalsTaxes for legal professionals can be complex, especially when considering different practice structures (e.g., sole proprietorship, partnership, or corporation) and revenue streams.
- Trust accounting has a well-earned reputation as a malpractice minefield that could jeopardize even the most carefully-run legal practices.
- This provides objective documentation of activities and the individuals who performed them.
- You should deposit any funds received on behalf of a client that aren’t immediately earned or allocated to cover expenses.
- By leveraging these resources and staying informed about evolving best practices in trust account management, lawyers can enhance their ability to uphold ethical standards and protect the interests of their clients.
- If you’re an attorney managing trust accounts, it is therefore very important that you understand trust accounting and how you can avoid common mistakes with this kind of accounting.
- By following the best practices outlined in this guide and staying informed about the latest technological advancements and regulatory changes, law firms can navigate the complexities of trust accounting with confidence.
Let’s dive into two specific types, IOLTA accounts and escrow accounts, and see how they stack up against a standard client trust account. Trust accounts often include separate accounts with large sums or pooled accounts that keep funds for more than a single client. Likewise, any checks issued should be immediately recorded in the check register. In all aspects of life, when you spot a contribution margin red flag, you ignore it at your own risk.
- This includes understanding the nuances of IOLTA accounts, record-keeping standards, and reporting obligations.
- Quite often, investigations aren’t triggered by lawyers playing fast and loose with the rules, but from the basic paper trail that is left by innocent mistakes made in management of an IOLA trust account.
- By avoiding these common pitfalls, you can ensure compliance with attorney trust account rules and maintain proper trust accounting practices.
- These resources offer detailed explanations of trust account rules, practical tips for maintaining compliance, and examples of common pitfalls to avoid.
- Therefore, it is imperative for lawyers to understand the potential consequences of violating trust account rules and take proactive measures to ensure compliance with these regulations.
- This step is crucial for maintaining transparency and trust in your client relationships.
- This includes promptly notifying clients upon receiving or disbursing their funds, obtaining proper authorization for withdrawals, and never using client funds for the operation of the law firm or for personal purposes.
- Key considerations include choosing a compliant financial institution familiar with the legal sector’s needs and ensuring that the account is correctly titled to reflect its purpose as a trust.
- Attorneys must maintain Lawyer Trust Accounts (IOLTAs) to hold a client’s funds until disbursement.
- State regulations often specify the types of records that must be maintained, the format, and the duration for which they should be kept.
- By effectively managing these accounts, lawyers uphold their ethical obligations and play a part in ensuring that legal services are accessible to those in need, reinforcing the profession’s role in serving the public good.
- Successfully managing trust accounts requires a thorough understanding of the rules and regulations that govern trust accounting.
Operating funds are the lifeblood of the law firm – used for Food Truck Accounting salaries, rent, utilities, and general business expenses. In practicing ethical client trust accounting there should be a positive balance if a firm/proprietor is holding client funds yet to be earned or a zero balance if all client funds held have been earned and are not subject to dispute. Under California’s Rule of Professional Conduct, 1.15 (c) (2) the only time a firm/proprietor should move client money from an account is when it is earned. If any amount of the fee is in dispute, such funds should be kept in the client’s trust account until the dispute is resolved.
Part of the issue is that the balance in a trust account isn’t always an accurate trust accounting for lawyers reflection of the matter balance. To determine the matter balance, you also need to factor in accounts receivable and works in progress (WIP). This means that you need your billing and accounting systems to speak to one another, or you need to be doing the cross-referencing yourself regularly.
Trust Accounting: Everything Lawyers Need to Know

Maintaining adequate records is imperative for helping your firm avoid these types of violations and for providing an audit trail for the tracking of client funds. This is especially important at large firms with multiple locations, where record-keeping can be complex. Remember, the goal is not just to comply with regulations but to excel in your fiduciary duties, enhancing your firm’s reputation and client relationships. Start your journey towards impeccable trust accounting and enhanced operational efficiency by trying out RunSensible’s Free Trial today.

Effortless Trust Accounting With LawPay


Mishandling client trust accounts can result in serious financial trouble for law firms and attorneys. Trust accounts require constant supervision to ensure client funds are allocated correctly, and managing trust accounts by hand can be challenging. When handled properly, this clean separation of funds ensures compliance with attorney trust account rules, maintains ethical behavior, and reduces the possibility of legal troubles.